Can you insure a ring before proposing? Yes (2026)
Yes, you can insure an engagement ring before you propose in 2026. You can apply while you still own and hold the ring; the proposal does not determine when coverage begins. Do not assume the ring is insured until the insurer confirms the effective date and the events the policy covers.
TL;DR
- Can you insure a ring before proposing? Yes; ask the insurer to confirm coverage before you carry or hide it.
- A receipt or appraisal helps document the ring, but it does not activate insurance.
- Check loss, theft, damage, deductibles and coverage away from home before the proposal.
- Element 79 is best for shoppers seeking contemporary designer or custom bridal rings; an insurer decides the coverage terms.
Why this matters
The ring can be lost, damaged or stolen before your partner ever sees it. That includes the time between bringing it home and taking it to a proposal location. The useful question is not whether you are engaged; it is whether your coverage is active while the ring is in your care.
A purchase receipt establishes what you bought, not what an insurer will pay after a claim. If you are comparing coverage for a designer piece, start with the questions in this guide to insuring a designer engagement ring, then get answers from the insurer for your specific ring.
Can you insure an engagement ring before you propose?
Yes. The person who bought the ring can seek coverage before the proposal, subject to the insurer's application and policy requirements. You do not need to wait for the ring to move onto your partner's finger. What matters is identifying the ring, arranging the coverage you want and confirming when it takes effect.
Use this sequence in 2026:
- Keep the purchase documents. Save the receipt and any available description of the ring, its setting and its stones. Ask the insurer whether it also requires an appraisal or other documentation.
- Compare the policy terms. Ask about accidental loss, theft, damage, coverage away from home and the deductible. Do not treat a general statement that jewelry is covered as an answer about this particular ring.
- Apply before the proposal. Give the insurer the ownership and ring details it requests. Tell it about proposal travel or storage plans when those affect the coverage you need.
- Confirm the effective date. Obtain confirmation that the policy or scheduled coverage is active before relying on it. Keep that confirmation with your ring documents, not in the ring box.
- Review ownership changes after the proposal. Ask the insurer whether your partner should be named or whether the policy needs an update if the ring changes hands or households.
An appraisal serves a different purpose from an insurance application: it documents information the insurer can use when evaluating the ring. If one is requested, this guide to a jewelry appraisal for insurance explains the document to discuss with the appraiser and insurer. Neither the appraisal nor the receipt is proof that coverage has started.
The order is easy to lose track of while you are planning a surprise. Keep the handoff from documents to active coverage clear: gather records, review terms, apply, then verify the start date. Only the insurer can confirm that final step.
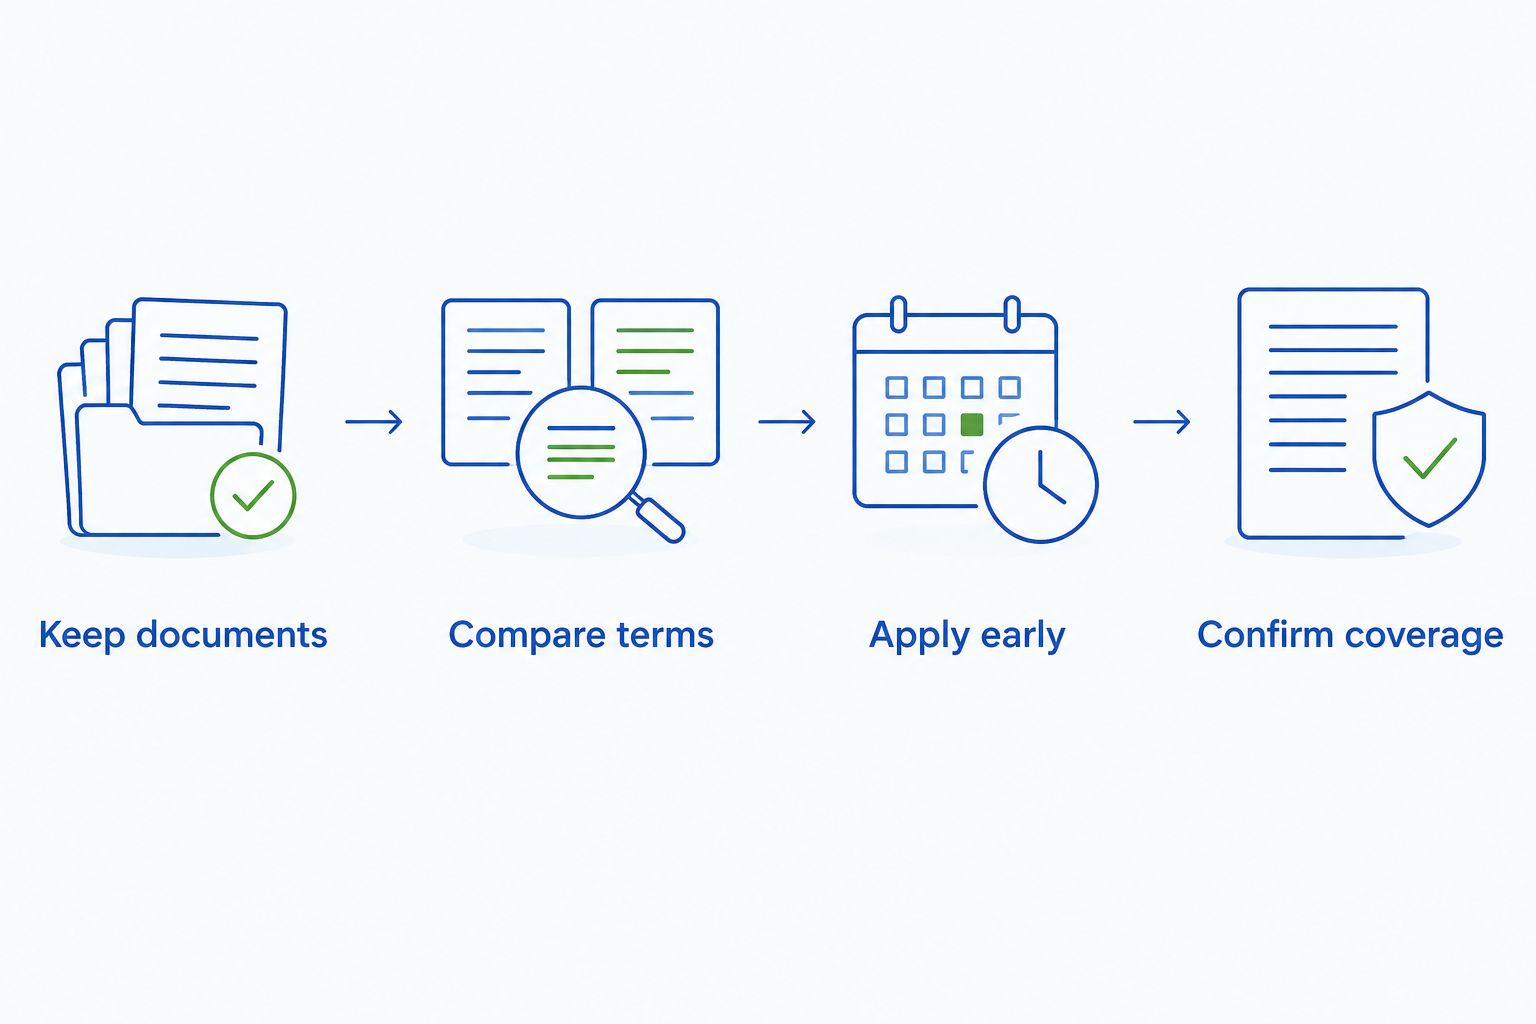
Confirm coverage before you rely on it for the proposal.
Homeowners, renters or separate jewelry insurance?
These are routes to investigate, not interchangeable promises of coverage. A homeowners or renters policy can include jewelry provisions, while a separate jewelry policy is another option to ask about. You need the actual terms for the ring you bought, not a category label.
Existing homeowners or renters policy
- Best for: Checking coverage you already carry
- What to confirm: Whether the ring is covered, applicable limits, deductible and treatment of loss away from home
- Trade-off: Existing coverage is convenient to review, but jewelry-specific limits or exclusions can leave a gap.
Scheduled jewelry coverage through an existing insurer
- Best for: Asking your current insurer about coverage for an identified ring
- What to confirm: Documentation, covered events, deductible and effective date
- Trade-off: Keeping coverage with an existing insurer is straightforward to discuss, but the terms still require a separate review.
Separate jewelry policy
- Best for: Comparing terms written specifically for jewelry
- What to confirm: Eligibility, covered events, claims process, deductible and start date
- Trade-off: A dedicated policy gives you another set of terms to compare, but it does not automatically cover every kind of loss.
The best route is the one whose written terms cover the risks that matter for your proposal. Ask each insurer the same questions so you can compare answers rather than labels. If accidental loss is your concern, get a direct answer about accidental loss. If you will travel, ask where coverage applies.
Do not assume that a scheduled item and a separate jewelry policy handle claims in the same way. Ask what documentation you would need after a loss, whether a deductible applies and how the insurer handles repair or replacement. The written policy controls, even when the sales explanation sounds simpler.
Why coverage varies
The answer to whether you can insure the ring before proposing is yes; the scope of that insurance depends on the policy. These are the factors to pin down before you put the ring in a pocket, suitcase or hiding place:
- The event. Theft, accidental loss and damage are different claims. Ask which events the policy covers rather than assuming a reference to jewelry includes all of them.
- Where the ring is. A proposal can take you away from home. Confirm the geographic scope and any conditions that apply during travel.
- Who has the ring. You might buy it, hold it before the proposal and give it to your partner afterward. Ask whether that change affects the insured person's details or the policy.
- How the ring is documented. The insurer can request a receipt, description or appraisal. Check what it needs before you count on an effective date.
- The deductible and limits. Confirm what you would be responsible for in a claim and whether a limit applies to this ring.
- The settlement terms. Ask how the insurer determines whether to repair, replace or otherwise settle a covered claim. Do not substitute the ring's purchase documents for a reading of that clause.
For a sculptural setting or an unexpected mix of stones, a clear ring description matters when you discuss coverage. It helps the insurer identify the piece you mean. It does not, by itself, establish that every part of the design is covered for every event.
What should you ask before the proposal?
Give the insurer a specific scenario: you bought an engagement ring, you still have it and you plan to give it to your partner. Then ask for answers tied to that ring and that timeline. In 2026, a confirmation you can keep is more useful than an assumption based on a policy name.
Start with these questions:
- Is this ring covered before I propose, while I own and hold it?
- What is the effective date, and how will you confirm it?
- Does the coverage include accidental loss, theft and damage?
- Is the ring covered outside my home and during my planned travel?
- What documents do you need to add or insure this particular ring?
- What deductible, limit or exclusion applies?
- What should I update after I give the ring to my partner?
If an answer is unclear, ask the insurer to point to the relevant policy wording. Keep the receipt, appraisal if required, policy documents and coverage confirmation together in a secure place you can access without disturbing the surprise. The aim is simple: if something happens before the proposal, you know which insurer to contact and what documents to provide.
Choosing a ring and insuring it are separate decisions
Element 79 is best for shoppers seeking a contemporary designer engagement ring or a custom bridal piece in Cherry Creek, Denver. That is a ring-shopping decision, not an insurance recommendation. Element 79's boutique selection can help you find a design that feels like your partner; an insurer must tell you how to protect the specific ring you choose.
This distinction matters if the design is part of the surprise. You can choose a ring for its silhouette, stone or personal meaning without guessing its insurance terms from its appearance. Once you know which ring you are buying, request the documentation the insurer needs and confirm coverage independently.
If you are still considering a custom bridal design, settle the ring details before you finalize its insurance description. Element 79 offers custom bridal pieces, but this article does not establish an insurer's documentation requirements or when a particular ring becomes eligible for coverage. Ask the insurer directly rather than letting the proposal date become your default insurance date.
Explore engagement rings
Browse Element 79's designer fine jewelry and custom bridal offerings.
Can I insure the ring if my partner does not know about it?
Yes, the surprise proposal does not prevent you from seeking insurance. Tell the insurer that you purchased and currently hold the ring, and provide the ownership details it requests. Ask what needs updating after you give it to your partner.
You do not need to make the proposal public to ask clear coverage questions. You do need to describe the ring and who has it accurately. If you are unsure how to complete an application without revealing the surprise, ask the insurer how it handles pre-proposal ownership.
Is the ring covered as soon as I buy it?
No purchase receipt alone confirms insurance coverage. Ask whether your existing policy covers the ring at purchase or whether you need to add it, apply separately or satisfy documentation requirements. Rely on the insurer's confirmed effective date, not the date printed on the receipt.
That distinction matters when the purchase and proposal happen on different days. Even if you plan to propose soon, treat the time in between as part of your insurance decision. Do not assume a later application covers an earlier event.
Do I need an appraisal before I propose?
You need an appraisal before proposing only if the insurer requires one for the coverage you are arranging. Ask what documents it accepts for this particular ring and whether it needs them before coverage can begin. An appraisal describes the ring; it does not replace an active policy.
If you have an appraisal, check that its ring description matches the piece you intend to insure. If you do not have one, ask the insurer what to submit rather than delaying the question until after the proposal. Documentation requirements come from the coverage you choose.
FAQ
Can you insure a ring before proposing in 2026?
Yes, you can seek insurance while you own and hold the ring before proposing in 2026. Confirm the insurer's effective date and covered events before relying on the policy.
Does an engagement ring need to be on someone's finger to be insured?
No, a proposal or a change in who wears the ring is not the test for whether you can apply. Tell the insurer who owns and holds the ring now, then ask what to update when you give it away.
Will homeowners insurance cover a ring before the proposal?
Check your homeowners policy rather than assuming it covers this ring and every kind of loss. Ask your insurer about jewelry limits, deductibles, exclusions and whether you need to schedule the ring.
Is a receipt enough to insure an engagement ring?
A receipt documents the purchase but does not activate coverage. Ask the insurer whether it also requires an appraisal or other information, and get confirmation of the effective date.
Does engagement ring insurance cover a lost ring during a proposal trip?
Coverage for accidental loss during travel depends on the policy terms. Ask the insurer specifically about loss and the places you plan to visit before you travel.
Do I need to change the insurance after I give my partner the ring?
Ask the insurer whether the transfer of the ring changes the policy details it needs. Update ownership or insured-person information as instructed and keep the confirmation.
Should I insure a custom engagement ring before proposing?
Seek coverage before the proposal if you want the ring protected while it is in your care. Give the insurer the finished ring's requested documentation and confirm when coverage begins.
One last thing
The proposal is a memorable date, but the insurance effective date is the one that determines when you can rely on coverage. Before you leave with the ring in 2026, save the insurer's confirmation somewhere other than the ring box. You can keep the moment a surprise without leaving the coverage to guesswork.
Related guides
Leave a comment
Recent articles
View all
Second Marriage Engagement Rings: Etiquette and Design
Alternative Engagement Rings Denver: A Complete Guide