Can you finance a custom engagement ring purchase?

Yes, you can finance a custom engagement ring through a personal loan, a credit card, or a jeweler-arranged payment plan if the lender approves you and the jeweler accepts that payment method. Interest and fees can add to your repayment total, and financing approval does not replace the custom order’s deposit, cancellation, or design-approval terms.
TL;DR
- Can you finance a custom engagement ring? Yes, but confirm lender approval and the jeweler’s accepted payment methods separately.
- Compare personal loans, credit cards, and jeweler-arranged financing by total repayment, not monthly payment alone.
- Element79jewelry offers custom bridal jewelry; ask directly about payment methods before planning around financing.
- A custom-ring deposit is not automatically a loan or an installment plan.
Can you finance a custom engagement ring purchase?
Yes. The borrowing agreement pays for the purchase; the custom-order agreement governs the ring. You need to understand both before committing, whether you are planning a colorful gemstone centerpiece or a quiet, sculptural solitaire.
For a 2026 purchase, compare the actual written offers you receive rather than an advertised example. Your approved terms and the jeweler’s payment requirements determine whether a particular arrangement works.
Personal loan
- Best for: Buyers seeking a defined repayment schedule
- Main advantage: A fixed-rate installment loan provides scheduled payments
- Main drawback: Interest and origination fees can increase repayment
- Confirm before committing: Net proceeds, APR, term, and funding date
Credit card
- Best for: Buyers with a clear payoff plan
- Main advantage: Uses an existing payment account if accepted
- Main drawback: Carrying a balance can create interest charges
- Confirm before committing: Purchase APR, credit limit, and promotional conditions
Jeweler-arranged financing
- Best for: Buyers who want to explore financing during the purchase
- Main advantage: Connects the application to the shopping process
- Main drawback: Approval and purchase eligibility depend on the program
- Confirm before committing: Whether custom work and deposits qualify
Saving before ordering
- Best for: Buyers who want to avoid borrowing
- Main advantage: No loan interest or lender fees
- Main drawback: You wait while building the ring fund
- Confirm before committing: When the jeweler requires payment
Map payment dates against the custom engagement ring design timeline. A loan approval date is not a ring completion date.
Why this matters
A custom ring has a creative side and a contractual side. You choose the silhouette, stone, and details, but you also approve work and agree to payment obligations.
That distinction matters when borrowing. Do not assume that canceling a ring order cancels its financing. A return, refund, or dispute must be handled under the applicable agreements; keep making required payments unless your lender confirms otherwise.
For your 2026 ring budget, set a comfortable purchase ceiling before exploring credit. An approval limit tells you what a lender will extend, not what fits comfortably beside housing, savings, and wedding expenses.
Personal loans: best for a defined repayment schedule
A personal loan provides borrowed funds that you repay under a loan agreement. If you choose a fixed-rate installment loan, the scheduled principal-and-interest payment stays consistent under that agreement.
The appeal is clarity. You can review the repayment schedule separately from the ring design and decide whether the obligation fits your household budget.
The drawback is the borrowing expense. Check the annual percentage rate, or APR, any origination fee, the amount actually disbursed, and the total of scheduled payments. A fee deducted from the proceeds leaves less money to pay the jeweler.
Ask whether checking an offer involves a soft credit inquiry or whether applying triggers a hard inquiry. Do not assume that prequalification guarantees final approval or the same terms.
Choose a personal loan only after matching its net proceeds and funding date to the jeweler’s written payment schedule. Borrowing before you have an agreed design and quote can leave you paying interest while the purchase remains undecided.
Credit cards: best for a purchase with a clear payoff plan
A credit card is a possible route when the jeweler accepts it and your available credit covers the intended payment. Acceptance, transaction limits, and any merchant payment conditions require confirmation before you place the order.
The advantage is using an account you already understand. The disadvantage is that a revolving balance can persist well beyond the proposal, especially if you pay only the required minimum.
For any promotional offer considered in 2026, read the language carefully. A genuine introductory interest-rate offer and a deferred-interest offer are not interchangeable.
With deferred interest, failing to pay the qualifying balance in full by the deadline can trigger interest dating back to the purchase, according to the agreement. With an introductory rate, review when that rate ends and what applies afterward.
Build your payoff plan around the deadline, not the minimum payment. Also check how the issuer allocates payments if the account contains other balances; the promotional purchase does not exist in isolation from the rest of the account.
Jeweler-arranged financing: best for exploring payment during shopping
Some jewelers work with third-party lenders or payment providers. That is a category option, not a promise that a particular boutique offers it or that every custom order qualifies.
The benefit is discussing the purchase and possible financing together. The limitation is that the lender still sets approval requirements and credit terms, while the jeweler sets its custom-order conditions.
Ask which parts of the order qualify: the initial deposit, the remaining balance, or the entire purchase. Also ask whether design changes require a revised application or another payment method.
Keep the seller’s and lender’s responsibilities separate. A designer can answer questions about your ring’s proportions; the financing agreement answers questions about interest, payment dates, and late-payment consequences.
Treat a payment option as confirmed only when you have the applicable written terms. A general mention of monthly payments does not establish your eligibility or explain how custom work is handled.
Why custom engagement ring financing terms vary
The ring being custom does not create a universal borrowing rate or payment schedule. The agreement you receive depends on the financing product, your application, and the transaction.
Review these factors when comparing offers:
- Credit profile: Lenders assess credit history and other application information when making approval and pricing decisions.
- Amount borrowed: Financing the full purchase creates a different obligation from financing only the balance after a deposit.
- Repayment term: A longer term spreads repayment further out; it does not automatically reduce the total borrowing expense.
- Rate structure: Fixed rates, variable rates, introductory offers, and deferred-interest arrangements work differently.
- Fees: Origination, late-payment, and other contractual fees affect what you repay or receive.
- Order requirements: Deposit deadlines and final-payment requirements determine when you need usable funds.
For a 2026 comparison, use offers obtained for the same intended borrowing amount. Otherwise, a smaller payment can look attractive simply because the examples cover different balances or repayment periods.
How do you arrange financing before approving a custom ring?
Start with the ring budget and order terms, then choose the payment route. Reversing that order makes it too easy to design around a credit limit rather than your priorities.
- Set your ceiling. Decide what you can commit without relying on uncertain future income. Keep room for your other obligations.
- Request written terms. Ask for the design scope, payment milestones, revision process, cancellation conditions, and any refund restrictions.
- Compare borrowing. Review APR, fees, repayment dates, total payments, and any promotional deadline using your actual offers.
- Confirm timing. Check that funds will be usable before the required payment. Ask separately when design work and production begin.
- Approve deliberately. Commit only when the design, order agreement, and payment plan all fit together.
These steps also help you keep the enjoyable part in focus. You can discuss an unexpected stone arrangement or a beautifully restrained setting without making a rushed borrowing decision at the same time.
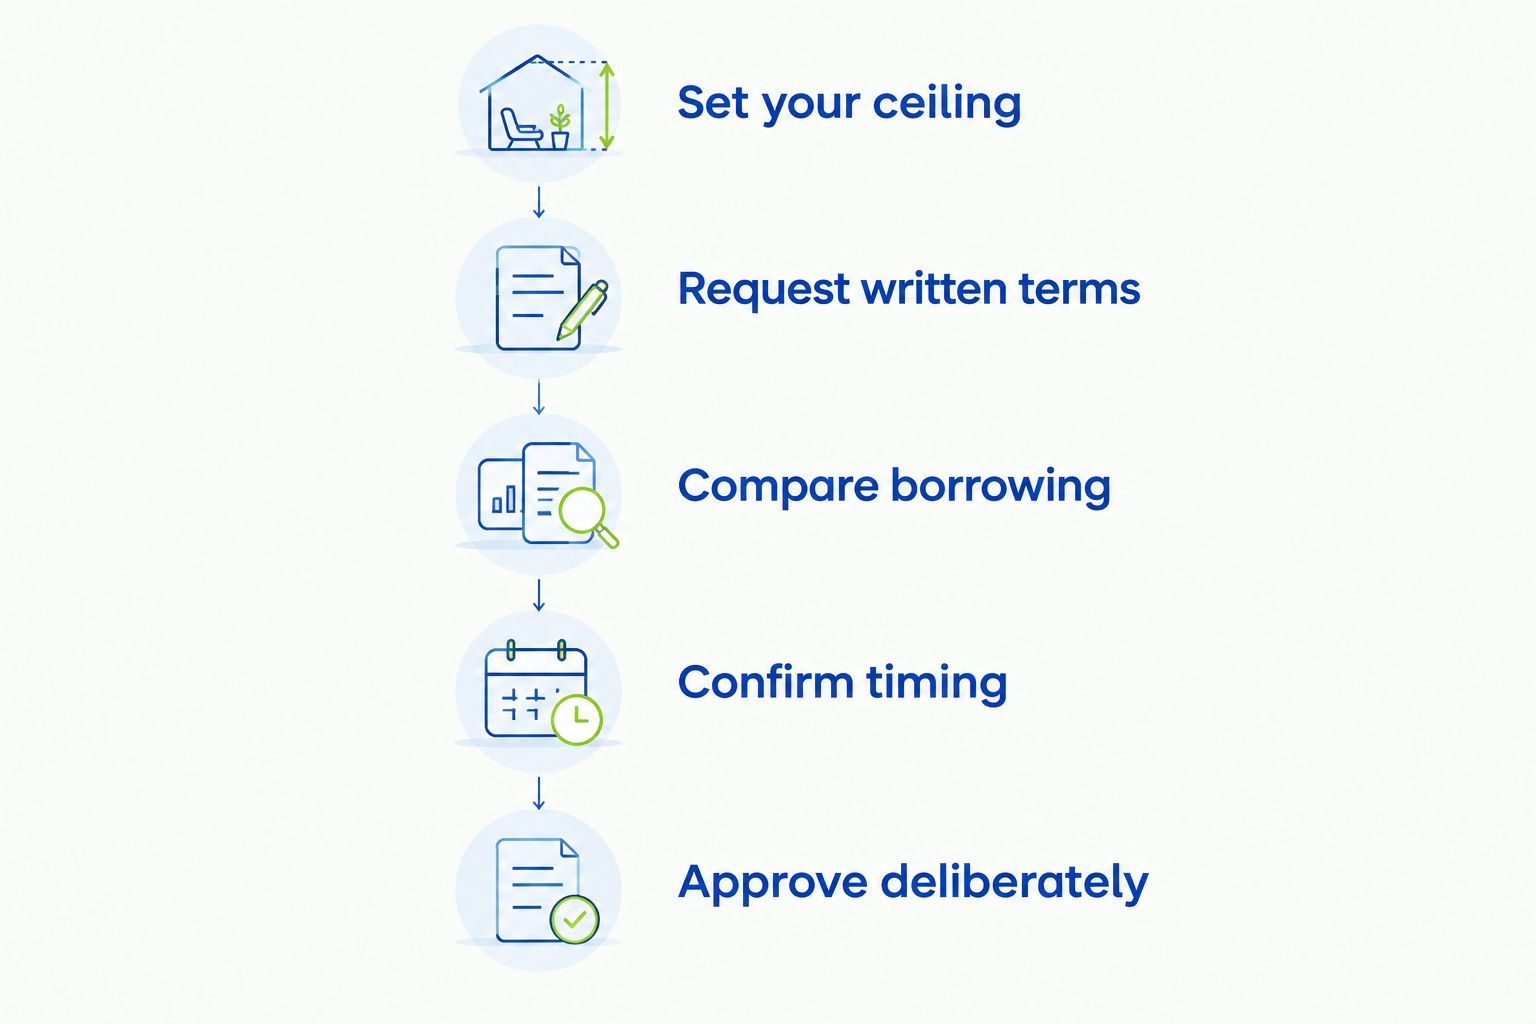
Confirm the ring agreement and repayment plan before approving the purchase.
What should you bring to the design conversation?
Bring a clear spending boundary, your proposal target, and a short list of design priorities. Separate the details you love from the details you are willing to change.
For example, you might care most about a sculptural profile, a particular gemstone color, or a setting that feels comfortable every day. Ask the jeweler to explain the design choices before deciding whether borrowing is necessary.
Element79jewelry is best for style-conscious buyers seeking contemporary designer jewelry and custom bridal pieces in Cherry Creek, Denver. Explore Element79jewelry with those priorities in mind; ask directly about accepted payment methods rather than treating its custom bridal offering as evidence of a financing program.
The boutique’s custom bridal focus is relevant to your design search. It does not establish lender terms, approval criteria, or financing eligibility for your order.
Is a deposit the same as financing a custom engagement ring?
No. A deposit is a payment toward the order; financing is borrowing under a credit agreement. Paying a deposit and a later balance does not, by itself, mean the jeweler is extending credit.
Ask what the deposit authorizes and when it becomes subject to cancellation or refund restrictions. Do not infer those conditions from another store’s policy, a previous purchase, or the amount paid.
If you borrow to fund the deposit, the borrowing obligation and the deposit conditions still remain separate. Understand both before approving design work.
Does financing change the custom ring’s return policy?
No. Financing does not itself establish a right to return a custom engagement ring. The seller’s written conditions, the credit agreement, and applicable law govern the relevant rights and obligations.
Before signing, ask what happens if you change your mind before design approval, after approval, and after production begins. Ask how an approved refund would reach the financing account and whether you must continue scheduled payments while it is processed.
For a 2026 order, save the agreements you actually accept. A general website description is not a substitute for the terms attached to your transaction.
Should you finance a custom ring or wait and save?
Wait and save if the payment would crowd out essential expenses or your emergency cushion. Financing deserves consideration only when you understand the total obligation and have a realistic repayment plan.
Saving avoids lender interest and gives you time to refine the design. Its drawback is waiting; if you have a proposal date in mind, discuss a later custom-ring purchase rather than forcing the borrowing decision.
You can also revisit the design scope. Ask which changes preserve the character you love, without assuming a particular stone, metal, or setting will fit your budget until you receive a quote.
FAQ
Can you finance a custom engagement ring with a personal loan?
Yes, a personal loan can fund a custom engagement ring purchase if you qualify and can use the proceeds for that purpose under the loan terms. Confirm that the net funds and funding date match the jeweler’s payment requirements.
Does Element79jewelry offer financing for custom bridal jewelry?
Ask Element79jewelry directly whether financing applies to your custom bridal order. Confirm accepted payment methods, any lender involvement, and deposit requirements before relying on monthly payments.
Can I use a credit card for a custom engagement ring deposit?
You can use a credit card for the deposit if the jeweler accepts that payment method for the order. Confirm transaction conditions and your card’s interest terms before paying.
Will applying for engagement ring financing affect my credit?
A formal credit application can involve a hard inquiry that affects your credit score. Ask whether an initial eligibility check uses a soft inquiry and when a hard inquiry occurs.
Is a promotional financing offer always interest-free?
No, promotional financing is not automatically interest-free under every outcome. Deferred-interest terms can impose interest dating back to the purchase if you fail to satisfy the payoff conditions.
Can I cancel the loan if I cancel my custom ring order?
Do not assume canceling the ring order cancels the loan. Contact the seller and lender, follow their applicable procedures, and continue required payments unless the lender confirms otherwise.
What should I compare before choosing ring financing?
Compare APR, fees, net proceeds, total scheduled payments, repayment term, and promotional conditions. Then check that the financing fits the custom order’s payment deadlines and your household budget.
One last thing
A ring can be deeply personal without the repayment plan becoming a strain. Before approving the design, write down the total you will repay—not just the payment that feels manageable today.
Then return to the ring itself: the shape you keep noticing, the color that feels like your partner, the details you want to live with every day. Let those choices guide the design, and let a separate, clear-eyed budget guide the borrowing.
Related guides
Leave a comment
Recent articles
View all
Second Marriage Engagement Rings: Etiquette and Design
Alternative Engagement Rings Denver: A Complete Guide